
News · Policy · Global
FSB Review Finds Slow Implementation Could Weaken Ability to Withstand Shocks
A review led by a former Federal Reserve official says national politics and law remain the larger reason post-crisis rules have been slow to take hold. But it finds that the Financial Stability Board’s own schedules sometimes overran the point where countries still wanted to act.
For information only. Not investment advice. Disclaimer
AI-generated summary, reviewed by the editor.
- A review led by former Federal Reserve official Randal Quarles found countries have been slow to adopt Financial Stability Board recommendations mostly for national reasons, such as legal frameworks.
- It also found the board's own timing sometimes outlasted political consensus, and proposes indicative timetables for new proposals, which it does not describe as binding.
- On crypto-assets, 11 of 28 jurisdictions had finalized a framework by the board's October 2025 check; the report does not say which countries are behind.
It restates the article and adds no new facts. How we use AI
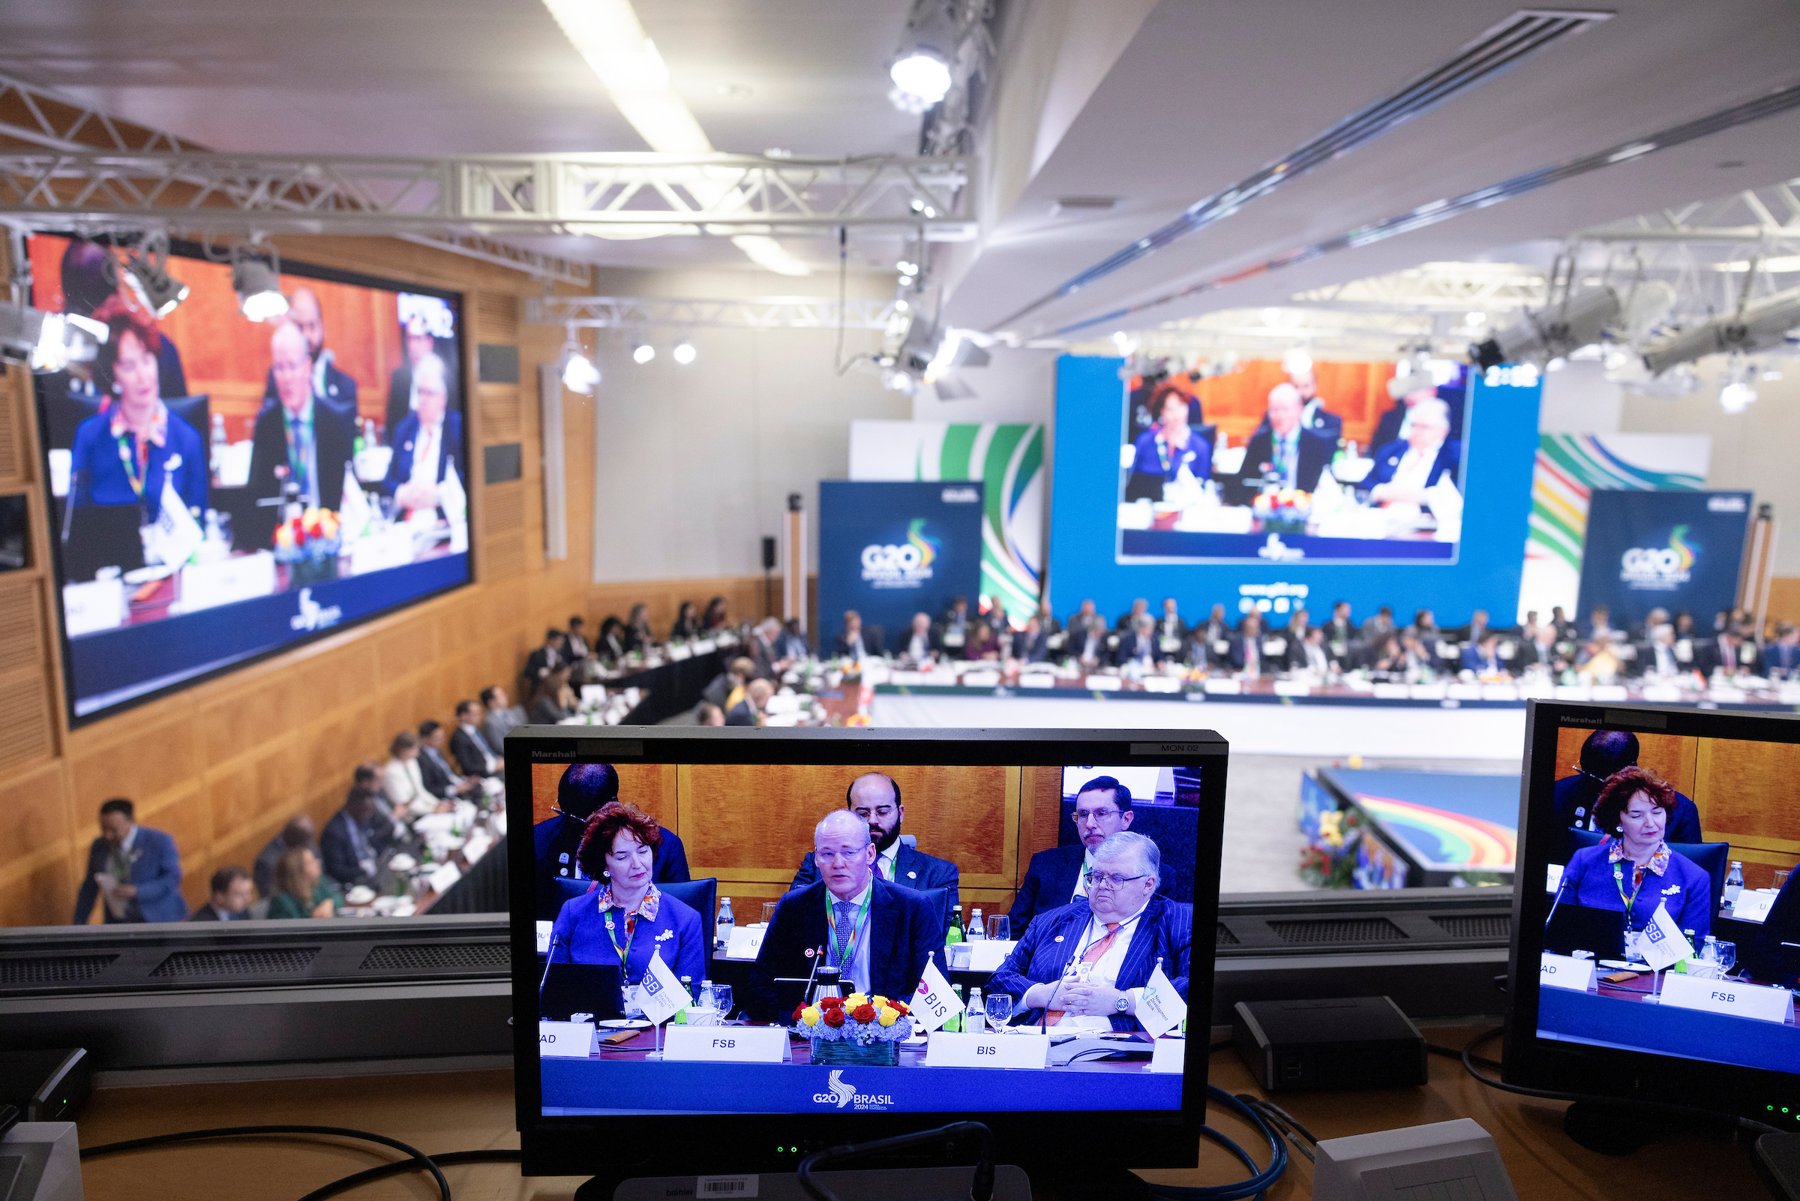
A review of the Financial Stability Board, the group that coordinates financial rules among the world’s major economies, has found that part of the trouble is the clock. In some cases, the review said, the time between spotting a risk and the deadline for countries to act was “long enough to outlast the political consensus that made agreement possible.”
The report, dated Oct. 14, was led by Randal K. Quarles, a former Federal Reserve vice chair for supervision who also once chaired the board. The United States, which holds the presidency of the Group of 20 major economies this year, asked for it.
Its main conclusion is a cautious one.
Countries have been slow to adopt the board’s recommendations mostly for reasons close to home. Mr. Quarles wrote in a foreword that national circumstances, including legal frameworks and market structures, “remain the larger determinants of where implementation has lagged.”
But the review also found “real, identifiable respects” in which the board’s own way of working made adoption “more difficult, or more contested, than it needed to be.” Timing came first on its list of six.
A Stitch in Time
The board is changing what it does. In announcing the review in June 2025, it said the key post-crisis reforms were developed or nearly complete, so its focus was shifting to promoting and monitoring how countries put them into practice. Mr. Quarles said he looked forward to leading “a balanced and independent review.”
The first stage, published in October 2025, didn’t hold back any punches.
It found that “recent trends indicate a worrisome slowdown in implementation, which could weaken the financial system’s capacity to withstand future shocks.”
Crypto-assets are a good example of what this means in practice.
The board finished its recommendations on crypto-assets in July 2023. Its October 2025 check, using information as of August 2025, found that 11 of the 28 jurisdictions it assessed had finalized a crypto-asset framework. Only five had finalized rules for so-called stablecoins, tokens designed to hold a steady value, usually against a currency such as the dollar. They were Bermuda, the Bahamas, the European Union, Hong Kong and Japan. The board described progress on stablecoins as slow.
Meanwhile the market grew.
Stablecoins totaled just under $290 billion in the board’s count, up almost three-quarters in a year. Those two dates, July 2023 and October 2025, are the 27-month gap charted below.
Curbing Your Enthusiasm
The Group of 20 created the board in 2009, in response to the global financial crisis. In those early years, the report says, rules moved forward under “strong political impetus and consensus.” That has faded.
The board’s job has changed, too. It once wrote rules for risks that had already caused a crisis. Now it spends more time on risks that might, such as those around crypto-assets, where the danger is harder to measure. The report says the methods built for the first job are “less well-suited to anticipating vulnerabilities that are contested, unquantified, and still developing.”
That makes speed matter more.
“In this environment,” the report says, the value of the board’s response “depends importantly on its timeliness,” because the “window of opportunity in which political will and consensus are sufficient to agree to a meaningful policy recommendation can be small.”
“In some cases, the interval between identifying a vulnerability and the agreed deadline for implementation of the policy recommendation has been long enough to outlast the political consensus that made agreement possible.”
The report does not name a case where that happened. It does say the timing, “unlike the underlying politics, is a matter within the FSB’s control.”
Put a Clock on It
The review’s answer is a timetable.
Each new proposal sent to the board’s top decision-making body would carry a schedule, running from the day the work is ordered to the earliest point at which the board might check whether countries have followed through. Members would weigh proposals knowing that, “all else equal, these timelines should be as short as possible.”
The report calls the timetables “indicative.” It does not describe them as binding.
Today the board’s habits vary.
Some of its documents name a deadline for countries to act. Others name only a time by which monitoring could begin. A 2010 document on derivatives called for a first progress report by March 31, 2011. A 2012 document on mortgage lending promised a follow-up review “after providing sufficient time for implementation,” with no date. A 2014 document on interest-rate benchmarks asked for a final monitoring report in 24 months.
The report’s timeline of the board’s published work shows how long the gaps can be.
Final proposals on money market funds came in October 2021, and a review of how countries had followed them came in February 2024. Final recommendations on crypto-asset activities came in July 2023, and a review of the crypto and stablecoin framework came in October 2025. Asian Value Investor’s count of the dates in the report puts the gaps at 28 months and 27 months. The report does not say whether either is too long.
Months from final recommendations to the first review of follow-through
Stop Reinventing the Wheel
The review makes five more recommendations.
Take on fewer topics: some board members warned that a longer agenda “may correlate negatively with effectiveness and implementation outcomes.” Start with broad principles and add detail as a risk becomes better understood. Ask outsiders, including officials from emerging economies, for their views earlier. Use consistent labels.
The board has called its recommendations by nine names, among them guidance, principles, standards and toolkits, and the report says “it may not be clear what distinguishes these formats.” And write down how recommendations get made, because “lessons learnt in one exercise have not reliably been carried into the next.”
Asian Value Investor’s tabulation of the report’s Annex 2 lists 65 board documents, and 2024 was the busiest year, with eight.
Documents listed in Annex 2, by year, 65 in all
None of that needs new institutions, Mr. Quarles wrote. “None of this calls for new machinery. It calls for more disciplined use of the processes the FSB already has.”
What This Means for the Average Investor
The board’s rules cover parts of the financial system where ordinary savings are at stake.
The report’s list of reforms includes bank capital rules, plans for winding down failing banks, derivatives and crypto-assets. Its timeline also takes in money market funds, funds that let investors withdraw while holding assets that can be hard to sell quickly, and a review of the market turmoil of March 2020.
Those rules protect investors only where countries adopt them. The report does not estimate what uneven adoption costs, and it does not say which countries are behind. That work is left to the 2027 report.
The link to everyday markets is already visible in stablecoins. The board’s October 2025 review said issuers hold large reserves in very short-term instruments, and that selling them quickly to meet redemptions could disrupt markets. The review said issuers are becoming significant players in traditional financial markets through those holdings.
A Review to Review the Review
The review is the second of three.
South Africa’s turn leading the Group of 20 produced a first look last year, which found “a worrisome slowdown in implementation.” Next year, the United Kingdom’s turn will bring a third report, due in the first half of 2027, on how the board tracks whether countries follow its rules. Timelines for that tracking may be explored there.
In Asian Value Investor’s view, if a full understanding of the problem has to wait for the third report, another crisis could arrive first, and the fixes it calls for may not be the ones the two reviews so far have pointed to.
The new report does not say which countries have fallen behind, on which rules, or by how long. That question, it says, “will be further examined in the next IMR report.”
Comments
Sign in with LinkedIn to join the discussion. Your LinkedIn name and photo appear publicly beside your comment. Please keep it civil and on topic.