
News · Markets · US
Michael Burry Says Nvidia’s Real Risk Is Bigger Than Jensen Huang
The investor who bet against subprime mortgages says the scandal around Jensen Huang distracts from a problem he has flagged for more than a year: a chip supplier building for demand that may not last.
For information only. Not investment advice. Disclaimer
AI-generated summary, reviewed by the editor.
- Michael Burry says Nvidia's real risk is the more than $170 billion it has put behind customers, a risk he flagged before Jensen Huang resigned.
- Nvidia shares closed Friday at $160.97, 33% below the Oct. 6 record close of $239.24. The stock fell 4.34% on Thursday, when Mr. Huang stepped down.
- Burry points to Cisco after March 2000 and to computer-leasing stocks, which fell about 80% by 1970, per Stocktwits, as precedents. Nvidia reports earnings Tuesday.
It restates the article and adds no new facts. How we use AI
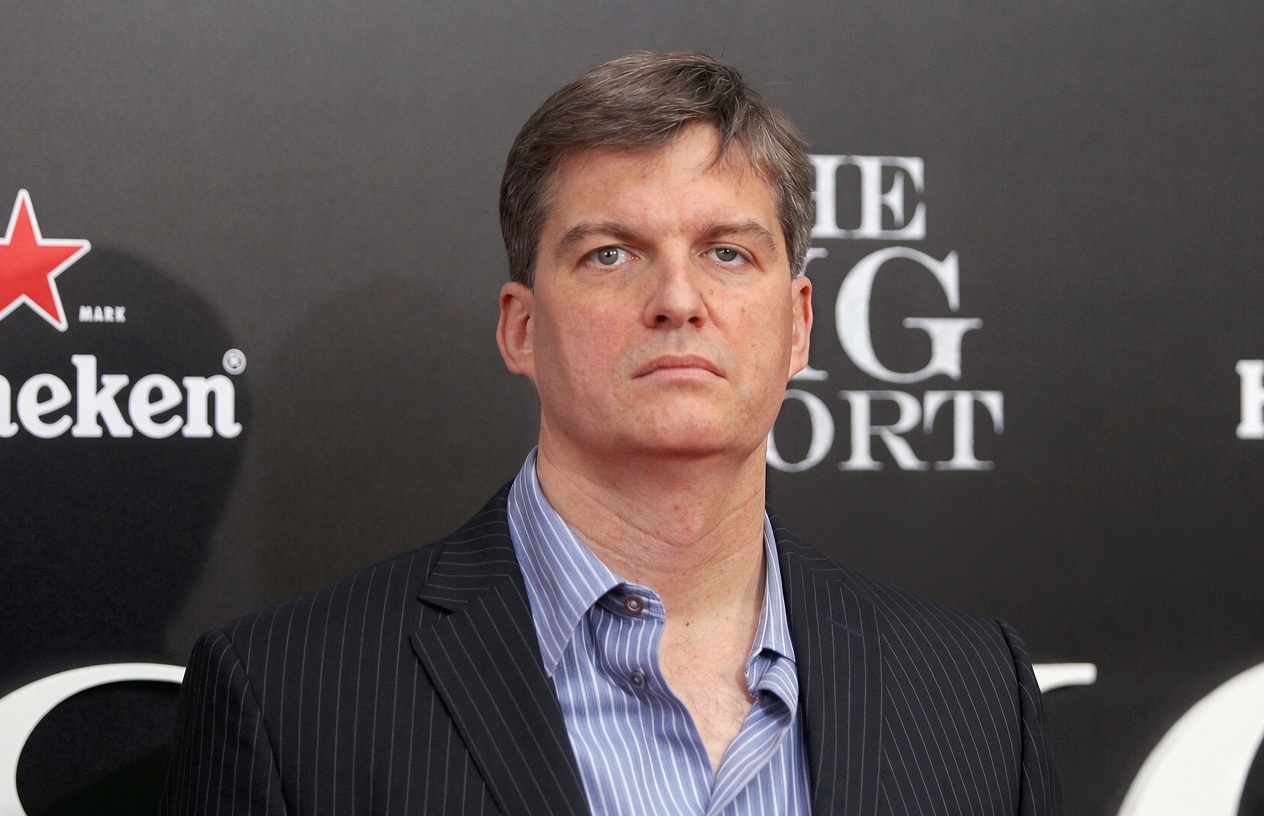
Michael Burry, the investor who called the 2008 Global Financial Crisis says investors may be missing the real trouble with Nvidia Corp. amid cofounder Jensen Huang affair with an alleged Chinese spy.
The investor who bet against subprime mortgages before 2008 and was portrayed in the 2015 film “The Big Short,” says Nvidia’s real risk is the exposure it has due to the more than $170 billion it has put behind customers, a risk he flagged long before Jensen Huang resigned as chief executive.
For more than a year he has argued that Nvidia’s business rests on a mismatch between the story being sold and the one forming underneath it. In a Substack post on Nov. 10, he said he does not expect the controversy around Mr. Huang to do much damage to the business itself.
Mr. Huang stepped down Thursday after 33 years as chief executive, and nearly all of the attention went to why. He admitted Sunday to being unfaithful to his wife. The Financial Times reported that he was involved with an executive at a Singapore cloud company whom U.S. intelligence officials believe works for China. The New York Times reported a second relationship, with a senior Nvidia executive who reports to him. Nvidia’s board, which opened an independent investigation Sunday, said it had “no reason to believe that either national security or NVIDIA secrets were compromised.”
Colette Kress, the chief financial officer since 2013, will act as the Chief Executive Officer of the company while keeping her finance role, Nvidia said. Harvey Jones, a director since 1993, became the board’s first chair and is expected to lead the search for a permanent successor.
The timing matters because Nvidia reports earnings Tuesday, its first test without Mr. Huang.
The stakes reach past one stock. Nvidia’s share of the advanced AI chip market is an estimated 90%, and spending on that hardware now shows up in the national accounts of the U.S. Asian Value Investor calculated that U.S. investment in information-processing equipment and software reached 5.35% of gross domestic product in the third quarter of 2026, above the 4.46% peak of the fourth quarter of 2000.
Nvidia’s market value of roughly $4 trillion gives it about 6% of the S&P 500 and about 10% of the Nasdaq 100, Leonard Gilroy of the Reason Foundation told Fortune. A sharp fall in the stock therefore reaches the index funds that hold it, and through them the 401(k) retirement accounts of ordinary savers. Jill Fisch of the University of Pennsylvania’s law school told Fortune that over the long term the effect “is going to be a tiny blip.”
A Third Off the Peak
Nvidia shares fell 4.34% on Thursday, at one point by more than 14%, and closed slightly above $4 trillion in market value. They closed Friday at $160.97, 33% below the record close of $239.24 on Oct. 6 and 14% below a year ago. CNBC reported that the stock had already fallen more than 20% in the month before Mr. Huang left.
View data
| Date | Close, $ | From record, % | Note |
|---|---|---|---|
| Nov. 13, 2025 | 186.86 | -21.9 | One year earlier |
| Aug. 3, 2026 | 206.64 | -13.6 | Shares keep climbing |
| Oct. 6, 2026 | 239.24 | 0.0 | Record close |
| Nov. 12, 2026 | 166.19 | -30.5 | Huang resigns |
| Nov. 13, 2026 | 160.97 | -32.7 | Latest close |
Neocloud stocks fell with it.
CoreWeave dropped about 9% Thursday and Nebius about 16%. Nvidia traded near $15 before ChatGPT launched, so even after the slide the shares sit roughly tenfold higher.
“Nvidia has committed to invest $10 billion in the Anthropic IPO. That will likely still happen when the IPO eventually happens,” said Francine McKenna, an accountant and investigative journalist who has taught at the Wharton School. “But anyone who was looking at Nvidia to bail out CoreWeave if needed should probably look elsewhere,” she told Fortune.
Funding the Customers
Nvidia has more than $170 billion on the line for neoclouds, the specialist AI cloud companies, and other large customers, The Information reported in October. As much as $164.5 billion of that is guarantees and other commitments tied to new data centers. Some are promises to pay landlords if tenants default on leases. Others are promises to buy computing capacity nobody else has bought.
View data
| Item | Amount | Note |
|---|---|---|
| Total on the line (neoclouds and other large customers) | More than $170 billion | The Information, via The Next Web, Oct. 23, 2026 |
| Guarantees and other commitments tied to new data centers | Up to $164.5 billion | No breakdown given in the report |
| Direct investments in AI cloud companies | More than $7 billion | Overlap with the $170 billion is not established |
Nvidia has also invested, or agreed to invest, more than $7 billion directly in AI cloud companies, according to The Information’s analysis of Nvidia’s filings. Whether the $7 billion sits inside the $170 billion is not established in either report.
“The demand for the neoclouds is off the charts.” Jensen Huang, to CNBC
Mr. Huang has also described financing hardware for customers as something that “is now becoming an asset class.” Meanwhile, CoreWeave shares have fallen 50% over six months.
The Wall Street Journal reported that this summer Mr. Huang cut off Ms. Kress mid-presentation to senior finance staff and called her “a deer in the headlights.” He called her more of a numbers reporter than someone who could help set strategy, according to the Journal’s account.
Ms. Kress had questioned Nvidia’s push to back billions of dollars in financing for customers that could not afford its chips, including deals led by Mr. Huang’s son-in-law Nico Caprez, who married Huang’s daughter, Madison Huang, in late September 2026. She also cut Nvidia’s initial commitment to a large OpenAI data center deal in half. Nvidia, Ms. Kress and Mr. Huang have not publicly responded to the account.
Nvidia closed at $206.64 on Aug. 3 and kept climbing until its Oct. 6 record.
Mr. Burry calls the arrangement circular, with customers “funded by their dealers,” and the resulting profits a “bezzle,” the economist John Kenneth Galbraith’s term for value that exists only until someone checks.
Nvidia has pushed back.
After Mr. Burry’s first public attacks, it sent Wall Street analysts a seven-page memo saying, among other things, that he had overstated its stock-based compensation costs. The real buyback figure was $91 billion, Nvidia said, not the $112.5 billion Mr. Burry used, because he included taxes on employee stock awards. Compensation, the memo said, is consistent with peers.
Mr. Burry had by then closed his fund.
He deregistered Scion Asset Management with the Securities and Exchange Commission in November 2025, citing “regulatory and compliance restrictions that effectively muzzled my ability to communicate,” and started a paid Substack, Cassandra Unchained. TechCrunch reported 90,000 subscribers in less than a week.
The Cisco Precedent
Mr. Burry cites Cisco in the late 1990s. The router maker supplied a build-out the market considered permanent, and customers over-ordered to secure scarce equipment. When demand cooled, Cisco wrote off more than $2 billion of inventory in 2001; CIO.com put the figure at $2.2 billion. Its stock peaked in March 2000 at $77.31 on a monthly-close basis. By September 2002 it was $10.48.
View data
| Month | Close, $ | Index (Mar. 2000 = 100) |
|---|---|---|
| March 2000 | 77.31 | 100.0 |
| September 2002 | 10.48 | 13.6 |
| December 2004 | 19.32 | 25.0 |
View data
| Episode | Period | Decline from peak, % | Index (peak = 100) | Basis |
|---|---|---|---|---|
| Nvidia, to date | Oct. 6 to Nov. 13, 2026 (about 5 weeks) | 32.7 | 67.3 | Close $239.24 to $160.97 |
| Cisco | March 2000 to Sept. 2002 (30 months) | 86.4 | 13.6 | Monthly close $77.31 to $10.48, split-adjusted |
| Computer-leasing stocks | 1968 to 1970 | About 80 | About 20 | Stocktwits’ account of Mr. Burry’s post |
Economists call the mechanism the bullwhip effect.
A small change in end demand becomes larger swings in orders as it travels upstream, because each link orders against the last link’s orders rather than against real consumption. Semiconductors are especially exposed, with lead times of six months to more than a year and fabs that cannot be turned down on a quarter’s notice.
Mr. Burry argues Nvidia sits near the tip of the whip.
He says Nvidia has committed to buy large quantities of wafers and memory from Taiwan Semiconductor Manufacturing Co. on terms it cannot cancel, that the chips are arriving faster than customers can absorb them, and that the biggest cloud companies are developing alternative silicon to depend less on Nvidia. He calls the pattern “supply-side gluttony.” Those claims are his.
His earlier argument concerns time.
Customers justify the cost of their graphics processing units, or GPUs, by assuming the chips will earn money for years. Mr. Burry says they overstate the useful life, and that newer generations make older chips uneconomic faster than depreciation schedules assume.
In a late-September Substack post he went after a slide in Nvidia’s investor presentation, which sets an assumed eight-year physical life against a five-year accelerated depreciation curve, which Mr. Burry called “apples-to-oranges.”
A chip that earns more than it costs, he wrote, “is a sign of scarcity due to memory and power shortages.”
He drew a second parallel, to computer-leasing companies in 1968, which undercut IBM by depreciating machines over eight years against IBM’s four. Their stocks fell about 80% by 1970, according to Stocktwits’ reporting of his post.
Mr. Burry has also changed his position.
Stocktwits reported Oct. 1 that he had covered short positions in common stock, Nvidia among them, and swapped the Nvidia short for September 2027 put options at strikes “in the mid $100s.” Yahoo Finance’s account of his Nov. 10 post says he replaced most of the Nvidia short with puts. The stock closed Friday at $160.97.
A Leadership Gap Before Earnings
That same post complicates the bearish read.
Nvidia could soon look like “a heck of a trade,” Mr. Burry wrote, per Stocktwits, though in Yahoo Finance’s account he added, “I am not tempted as a long-term hold from here.” He expects Nvidia’s competitive advantage to narrow over the next five years, both outlets reported. Stocktwits listed puts he holds on a semiconductor exchange-traded fund, the Nasdaq-100, Oracle and Palantir. It did not say whether the Nvidia puts remain.
Analysts who disagree with Mr. Burry about the business are no more upbeat about the leadership.
“Jensen is Nvidia, right? He is the visionary,” Stacy Rasgon of Bernstein told CNBC. The broker cut its price target to $200 from $400. Richard Reyle of Questar Capital Partners said the lack of a succession plan makes the stock “uninvestable.”
Meanwhile, Mr. Huang has left no heir apparent. He ran a flat organization of about 60 direct reports, owns about 3.5% of Nvidia’s shares and held no supervoting rights, so the board could have removed him at any time.
The Journal’s account puts him at the center of the financing push.
If that is right, customers who were pressed to sign may now feel freer to delay, renegotiate or buy elsewhere.
Nvidia’s revenue grew from $4.13 billion in fiscal 2014 to $215.9 billion in fiscal 2026, most of it on Ms. Kress’s watch as chief financial officer. In a staff memo reported by Entrepreneur, she said she would keep “building on the extraordinary foundation Jensen created.” The board is considering candidates from inside and outside the company and has not named a permanent chief executive.
Nvidia reports Tuesday.
Three House committee chairs have asked Mr. Huang for a closed-door briefing on Nov. 18. Mr. Burry’s puts, as Stocktwits described them, expire in September 2027.
Sources
- Nvidia’s Jensen Huang resigns, chipmaker names CFO Colette Kress as interim CEO (TechCrunch)
- Nvidia CEO Jensen Huang resigns: Live updates (CNBC)
- Why did Nvidia CEO Jensen Huang resign, and who is Colette Kress? (Al Jazeera)
- Nvidia’s Jensen Huang resigns, CFO Colette Kress named interim CEO (Fortune)
- Nvidia’s board, Jensen Huang and 401(k) retirement exposure (Fortune)
- Anthropic’s blockbuster IPO just got harder after Jensen Huang’s dramatic exit as Nvidia CEO (Fortune)
- Months Before His Fall, Jensen Huang Called His CFO ‘a Deer in the Headlights’ (Entrepreneur, relaying The Wall Street Journal)
- Nvidia has put $170bn on the line for neoclouds (The Next Web, relaying The Information)
- This Thanksgiving’s real drama may be Michael Burry versus Nvidia (TechCrunch)
- Michael Burry warns Nvidia, AI infrastructure expansion mirroring 1960s computer leasing bubble (Stocktwits via TradingView)
- Michael Burry says Nvidia could be ‘a heck of a trade’ (Stocktwits)
- Michael Burry has a surprising new take on Nvidia stock (Yahoo Finance)
- What went wrong at Cisco in 2001 (CIO.com)
- Why a Burst AI Bubble Could Feel Worse Than the Dot-Com Bust (Asian Value Investor)
- Former Nvidia Executive Sidelined Over Alice Huang (Asian Value Investor)
- Cassandra Unchained (Michael Burry’s Substack).
- Price data: Yahoo Finance, Nvidia daily closes (Nov. 13, 2025 to Nov. 13, 2026) and Cisco monthly closes (March 2000 to December 2004), split-adjusted. Calculations are the author’s.
Comments
Sign in with LinkedIn to join the discussion. Your LinkedIn name and photo appear publicly beside your comment. Please keep it civil and on topic.